How to Budget with an Irregular Income
Master freelance financial management with a reliable variable income budget. Learn how to set a baseline, build an income buffer, and automate savings today.
Whether you’re a freelancer in London, a gig worker in New York or a remote consultant in Europe, having variable income means you have ultimate freedom.
Until it comes to rent and clients hold off with payments.
Budgeting is always based around regular (9-5) income. If you have irregular income then traditional budgeting methods will quickly fall apart. This can cause you to feel stressed about how you’ll afford basic food items.
You won’t need a company salary to get on top of your money. You just need to be more strategic with your variable income.
Here is how to gain control of your money, even out your cashflow and put in place effective budgeting strategies with variable income. Mastering freelance financial management is the key to turning uncertainty into stability.
Why Traditional Budgeting Techniques Don’t Work for Independent Earners
Most budgeting guides will tell you to budget on a set income. They’ll encourage you to split your income into 50/30/20.
However, if your income is erratic, you can cause yourself stress. When you create a strict budget based on a specific income of $4,000 month, but reality delivers $2,000, you are left feeling like a complete failure and give up altogether.
You need to change your mentality. Instead of budgeting for each month based on income you’d like to receive, you’ll create a robust buffer based on your financial foundations by building a reliable variable income budget.
 Finnly Joy
1. Understand Your Baseline Budget
In order to manage your erratic income, you need to understand your bottom line. This is how much money you need to have in order to keep your household going without falling into high interest debt.
Look through your bank and credit card statements over the last 6 months. Separate your income into 2 categories.
- Essentials (These are non-negotiables): Rent/Mortgage, Utility Bills, Basic Groceries, Insurance, Minimum Debt Payments, Transportation.
- Discretionary (These are negotiable): Eating Out, Streaming Services, Travel, New Clothes & Entertainment.
Add up your Essentials. Let’s say you’re baseline is $2,500 (or £2,000 / €2,300).
This is your Baseline. The most important part of your finances. Anything else will come second until your baseline is met. Knowing you’ll always have this amount will make you feel relieved when you have a slow income month.
2. Create Your Income Buffer
Independent earners will struggle without an income buffer.
An income buffer is essentially money in your savings account that separates your earning and spending months.
- The Problem: You earn money in October but spend it in October. If you have a slow month, you’ll panic.
- The Solution: You live off last months income.
All the money you earn in the current month goes into a savings account. On the first day of next month, you’ll take a snapshot of your total. This is your spending amount for next month.
By living off last months income, it doesn’t matter if you have a client that takes 30 days to pay you as you have money saved from previous work.
3. Pay Yourself A Regular Corporate Salary
The biggest mistake people make when having an income that varies is overspending when they get a big contract. You get paid $6000 in 3 weeks and blow it all on fancy gadgets and eating out. Then you panic for the next 2 months.
Never treat your business account like your personal account.
Pay yourself a regular and predictable salary based on how safe you want your money to be.
- Based on Your Slowest Months Rather Than Fastest: Don’t average out your fastest months, instead think about your slowest months from the past year, or your baseline.
- Have a Conservative Withdrawal: If your baseline is $2500 a month, pay yourself a regular salary around that amount (or a bit more if your cashflow allows it). Never pay yourself a regular salary based on your highest earning months.
- Automate It: Automatically pay yourself a set and predictable amount from your business account into your personal account.
This way if you have an above average month you will still have extra money in your business account. This creates a great buffer that ensures you will always be able to afford to pay yourself a salary during slower months.
 Finnly Joy
4. Automate Your Tax & Wealth Building
If you’re working independently in the US, UK or Europe, tax time can be stressful. When working traditionally, your employer will automatically deduct taxes from your pay. As a self-employed person, you will need to pay taxes such as IRS quarterly estimates or HMRC self assessments.
Never leave money in your main account without paying tax. As soon as you receive payment from a client, split your money into:
- Tax: Put 25%-30% into your tax savings account. This is not yours as it legally isn’t.
- Wealth Building: Put 10% into your tax advantaged accounts. In the US, this could be your Roth IRA or traditional IRA. In the UK, make sure you maximise your Stocks and Shares ISA or SIPP.
- Overheads: A small amount for software and tools.
- Living: The rest will go into your personal account for your living expenses.
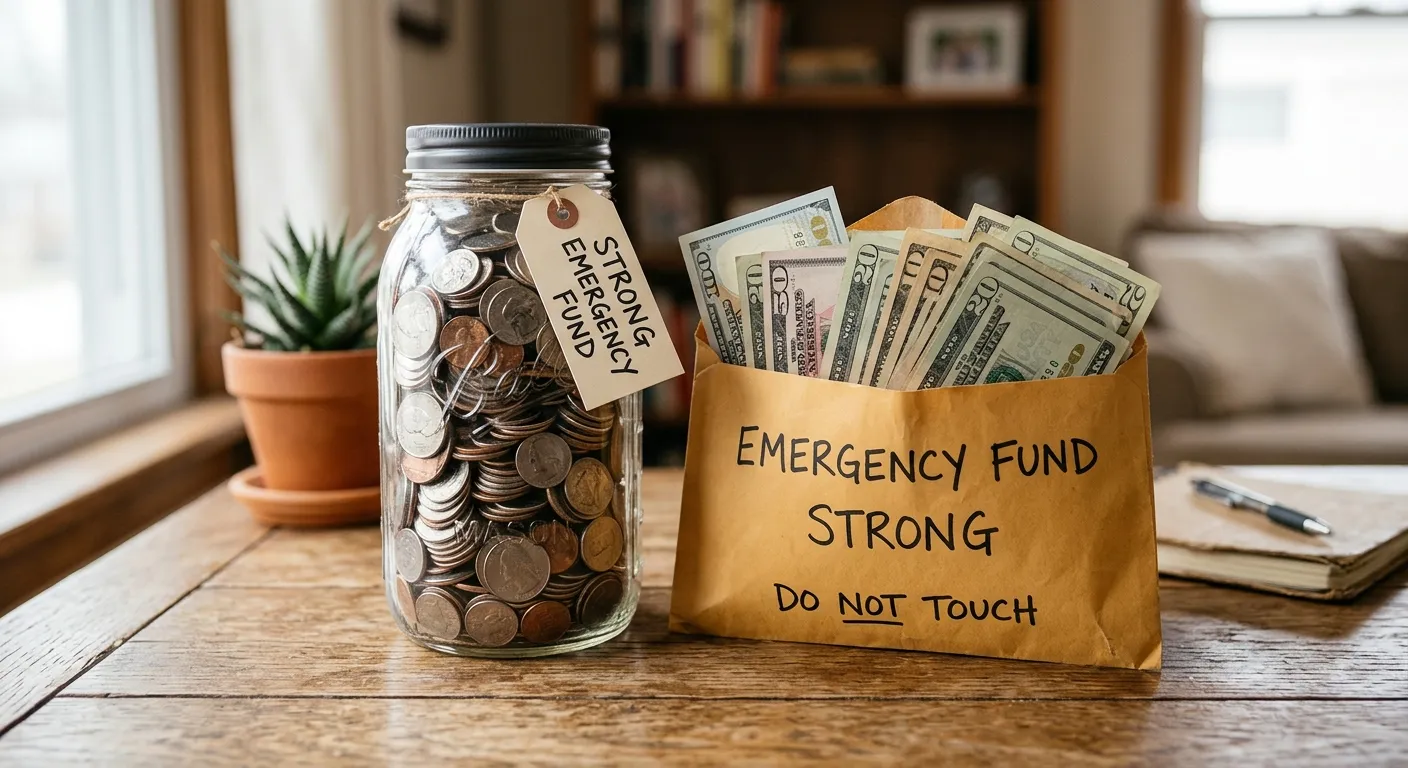
5. Create a Strong Emergency Fund
Your baseline buffer will help with short term fluctuations, but what if there is a downturn in your industry and you stop working for 3 months? Or you have an unexpected health issue?
You need to create a strong emergency fund. For independent workers, having a dedicated emergency fund for freelancers is non-negotiable.
Traditional employees are advised to save 3-6 months of living expenses. Those with erratic income should aim to save 6-9 months of essentials.
Save your money in a high yield savings account (HYSA). This way you’ll earn a good rate of interest but still have easy access within 24 hours. Don’t put your money in risky investments as this is your safety net.
6. Know How To Manage Variable Costs
If you have a variable income, your costs should also be variable.
- Fixed: Your rent, insurance, loan payments and communication costs will be the same regardless of how much you earn in a month ($1,000 or $10,000).
- Variable: Groceries, Eating Out, Entertainment & Shopping.
During high income months, you can spend on higher quality food, pay down debt and invest. During low months, you can easily reduce your variable costs. Cook at home, cancel subscriptions and reduce spending.
Budgeting Checklist For Independent Earners
Use this list to ensure you’re creating the best cashflow possible.
[ ] Understand your exact monthly essentials.
[ ] Open 2 bank accounts.
[ ] Create a 1 month income buffer so you’re living off last months income.
[ ] Create a conservative monthly salary.
[ ] Automate your tax by splitting your money into percentages.
[ ] Aim to save 6-9 months of essentials.
Getting your head around a variable income will take some discipline. Your system won’t be perfect during the first month. You may not get your baseline correct or struggle to create your buffer.
This is completely fine.
You don’t want a perfect system – you want a system that will help you. By creating a buffer, paying yourself a regular salary and automating your taxes, your erratic income will no longer cause you stress. You’ll stop worrying about when you’ll get your next payment and start focusing on developing your craft, growing your business and enjoying the true freedom of being independent.
Stay happy and wealthy,
Finlly Joy
 Finnly Joy
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be construed as professional financial, investment, or legal advice. Financial situations and credit scoring algorithms vary by individual and location. Always consult with a certified financial advisor or credit professional before making any major financial decisions.