How to Set Realistic Financial Goals That Actually Stick (Without Burning Out)
Tired of breaking your New Year's financial resolutions? Learn how to set realistic money goals, build practical wealth habits, and protect your purchasing power.
Every year when December/January comes round we all plan “perfect” financial goals for ourselves:
“I will save 20% of my income this year!”
“I’m going to pay off my debts earlier.”
“I will put 100% of my retirement into my retirement accounts each month.”
However a few weeks down the line we’ll be hit with reality as inflation rises, utility bills increase and we get unexpected costs, our perfect spreadsheets won’t stand a chance.
The truth is having successful financial goals isn’t about having perfect predictions. It’s about creating a system that is easy to follow.
I’ll show you how to create realistic financial goals for next year:
1. Being realistic
An easy mistake to make here is to think you can make large financial goals happen quickly.
Unless you’re lucky enough to win the lottery no-one gets rich overnight, or even in a month. To really create wealth you need to be patient and consistent.
If you can’t accept that wealth will compound slowly then you’ll likely fall into the same trap of the rat race:
Earn a monthly salary
Pay off loans and bills straight away
Live paycheck to paycheck with nothing left.
Living in a constant state of financial stress.
Therefore you need to be a bit more educated in personal finance. Remember that creating wealth is a long term process.
 Finnly Joy
2. My personal approach
Keeping your goals in your mind or putting them in a forgotten file on your computer won’t help. I like to break my goals down into:
Break your financial goal into parts:
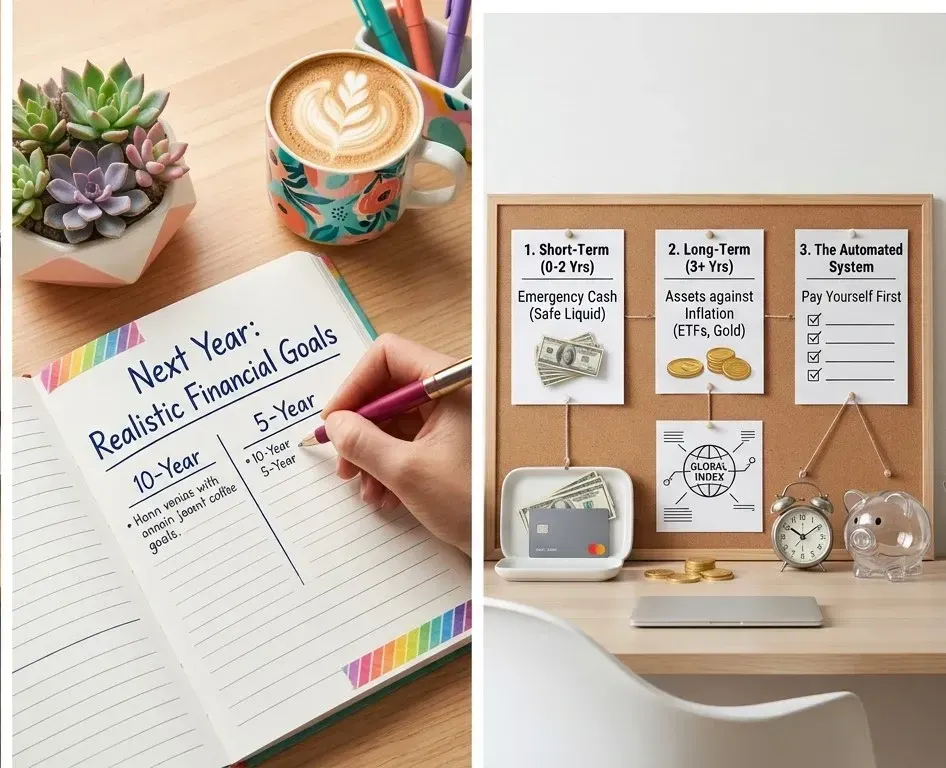
10 Year Goals (Long Term): Big life goals such as your retirement, buying your dream home or becoming completely financially free.
5 Year Goals (Medium Term): Saving for a deposit, starting a side hustle or paying off any large long-term loans.
1 Year Goals (Short Term): What you want to save in the next year, building an emergency fund or starting a side hustle.
Every year, I like to write my financial goals down in a physical journal alongside a clear, step-by-step plan of action. To make the vision even more real, I even paste a goal image right onto the page—such as a picture of the car I am working toward—so I can visualize my target every time I open my notebook.
Read through them every month: Every month I read through my journal. It acts as a personal to-do list. You cannot have your financial goals in your head or hidden away in a file on your computer. They must be visible so you can see what you're doing.
When I put my goals in my physical journal, I tend to lay out a plan for my goals. For example, here is how I have laid out my goal to purchase a car:
My Car Purchase Goal
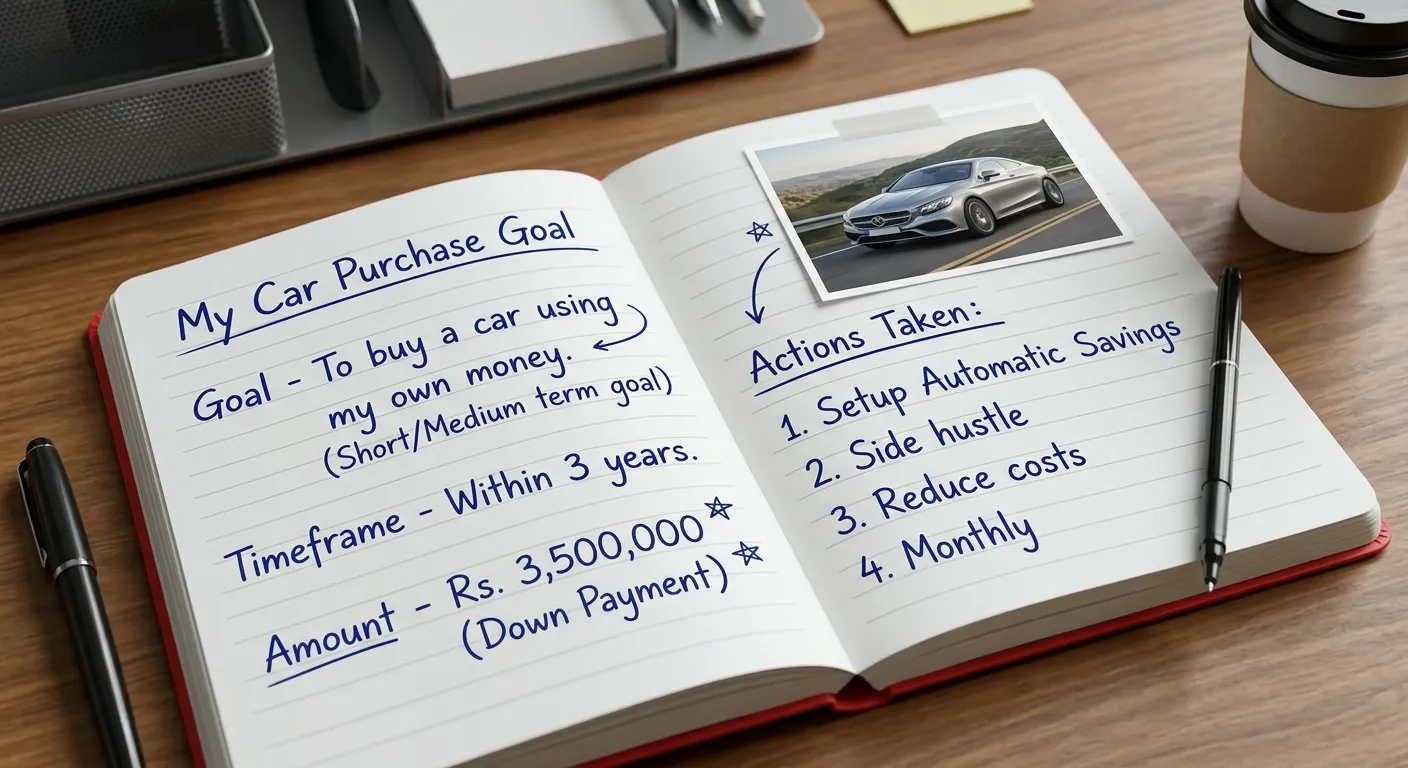
Goal – To buy a car using my own money. (Short/Medium term goal)
Timeframe – Within 3 years.
Amount – Rs. 3,500,000 (Down Payment)
Actions Taken:
Setup Automatic Savings – As soon as I receive my salary I use a standing order to automatically transfer an amount of money to my Car Fund.
Side hustle – I put 50% of my freelance income towards my car.
Reduce costs – I reduce unnecessary costs of everyday living and entertainment and put the amount I save into this fund.
Monthly – I look at my extra savings in my journal at the end of each month to track my progress.
Don’t feel guilty if you don’t meet a certain goal this year. Just move that goal into next years list and try again!
Once you’ve met a goal you’ve worked hard for use this to give you motivation to move onto your next goal.
3. Increase your income
Sometimes cutting your costs won’t be enough as you may be living a very minimal lifestyle. In this case, focus on increasing your income.
Make sure next year you include:
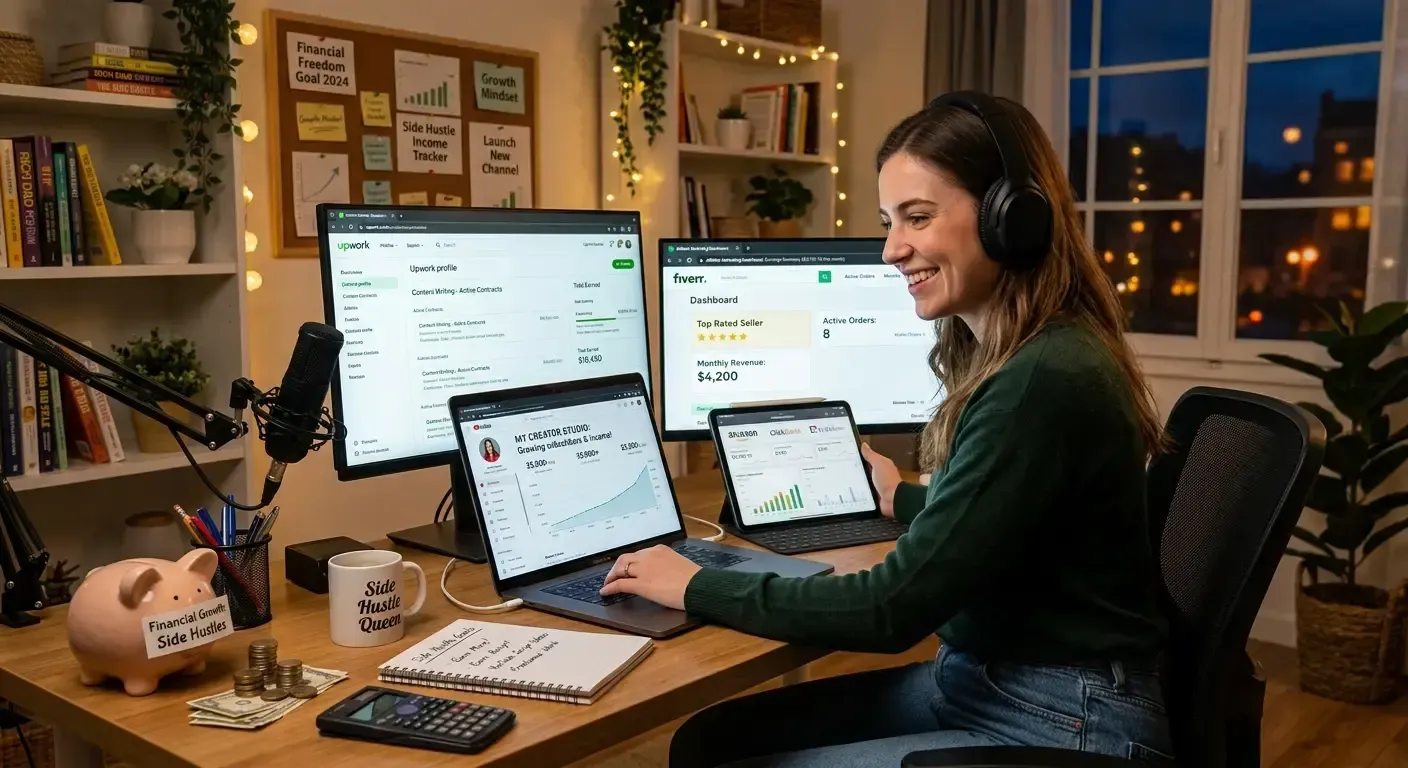
Start a side hustle: Think about what skills you have that can be marketed. Maybe you can freelance write, design digitally, tutor or offer online consultancy. Create an extra income stream.
Grow your own food: With food inflation rising, you can reduce your monthly grocery bills by growing your own vegetables, greens or fruit in your garden/balcony.
 Finnly Joy
4. Don’t fall for the paper wealth trap
Many people fall into this trap. They think that by increasing the number in their savings account they are increasing their wealth.
However if you’re saving in a high-yield savings account earning you 5% interest but the inflation rate and cost of living in your area is 7% then your money is losing value. You’re not able to buy as much bread, fuel or housing.
To avoid this:
Short Term (0-2 Years): Keep your emergency funds in a high yield savings account.
Long Term (3+ Years): Invest your money into assets that will help you fight against inflation such as global index ETFs, gold or tax advantageous retirement accounts.
5. Automate your wealth building
Trying to save each month using your willpower will be tough. Life can be very distracting. The secret to being a successful saver is to automate:
Pay yourself first: Setup an automatic bank transfer (Standing Order) to automatically move the percentage you want to save/invest on the day your salary comes into your account.
Dollar Cost Averaging: Invest a set amount of money each month into a broad index fund.
Annual review: Choose one day of the year to review your portfolio.
6. Prepare for unexpected shocks
Life can throw unexpected surprises. Ask yourself:
If your main source of income stopped tomorrow, do you have 3-6 months of essential living costs saved away in an emergency fund? This way you won’t have to sell your long-term investments at a loss.
If rates increase or you have to pay more towards your debt, do you have enough breathing space in your household?
If the above makes you uncomfortable then your main focus for next year should be increasing your emergency cash and paying off your high interest debt.
New year checklist:
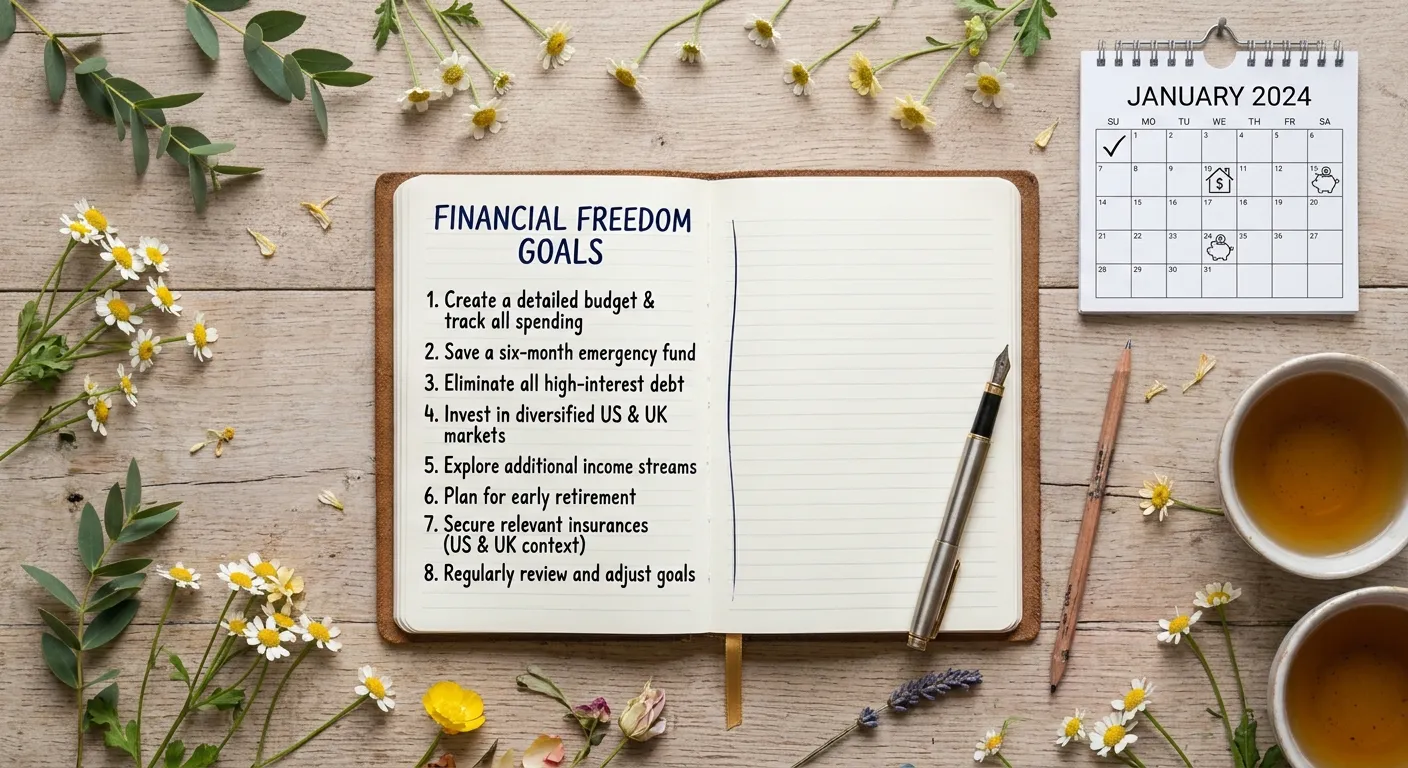
Tick off the below to set up your finances for next year:
[ ] Purchase a personal finance journal. Hand write your 10 year, 5 year and 1 year financial goals.
[ ] Add a calendar reminder. Add a recurring reminder on your phone to read through your journal on the last day of each month.
[ ] Plan a way to increase your income. Plan out how you’re going to start a side hustle or set up a garden.
[ ] Build an emergency fund. Save 3-6 months of living costs into a safe liquid account before investing.
[ ] Automate your savings. Set up automatic transfers for your savings and debt repayments.
[ ] Increase your knowledge. Read one personal finance book or financial management guide.
Having realistic financial goals isn’t about predicting what will happen with the economy or which stocks to invest in. It’s about taking control of what you can influence. Focus on increasing the amount you’re saving, being disciplined with your spending, increasing your income and creating good habits.
Pick up a notepad and plan out your goals. Let time and consistency work for you!
Stay happy and wealthy,
Finlly Joy
 Finnly Joy
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be construed as professional financial, investment, or legal advice. Financial situations and credit scoring algorithms vary by individual and location. Always consult with a certified financial advisor or credit professional before making any major financial decisions.